

Bài tập Derivatives CFA (Môn Công cụ phái sinh CFA) kèm đáp án
Nội dung chính
Các câu hỏi bài tập Derivatives CFA sẽ kiểm tra các kiến thức, hiểu biết của bạn về Chứng khoán phái sinh cơ bản, Hợp đồng kỳ hạn, Hợp đồng tương lai, Quyền chọn mua hoặc bán, Hợp đồng hoán đổi và cách định giá chúng. Ở trong bài viết này, TACA tổng hợp giúp bạn các bài tập của môn học này, cùng tìm hiểu nhé!
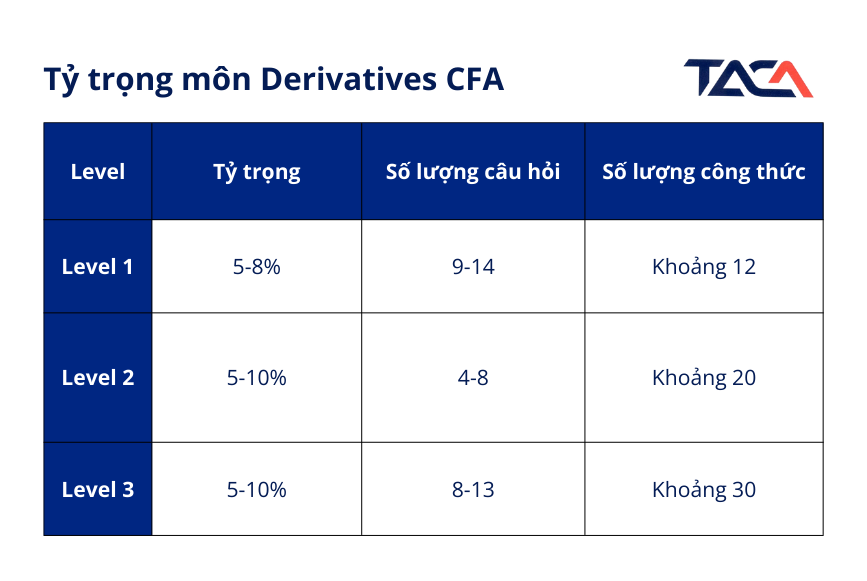
Với môn Derivatives CFA (Công cụ phái sinh), Viện CFA chia tỷ trọng trong các level như sau:
Xem thêm: Derivatives CFA (Môn Công cụ phái sinh CFA)
1. Bài tập Derivatives CFA Level 1
Question 1: All else held equal, the value of a European call option is best characterized as having a:
- negative relationship with the price of the underlying.
- negative relationship with the volatility of the underlying.
- positive relationship with the time to expiration.
Question 2: All else being equal, which of the following European put options on the same underlying most likely has the highest value?
| Time to Expiration | Exercise Price | |
| Option 1 | 2 months | $52 |
| Option 2 | 4 months | $52 |
| Option 3 | 4 months | $58 |
- Option 1
- Option 2
- Option 3
Question 3: The value of a European put is directly related to the:
- risk-free rate.
- exercise price.
- value of the underlying.
Question 4: An investor gathers the following information about a call option:
| Option premium | $5 |
| Exercise price | $25 |
| Price of the underlying at initiation | $15 |
At expiration, if the price of the underlying is $30, the value of the call option to the call seller is:
- -$5.
- $0.
- $10.
Question 5: An analyst gathers the following information:
| Call price | $10 |
| Stock price | $40 |
| Exercise price | $60 |
| Interest rate | 3% |
| Time to expiry | 1 year |
According to put-call parity, the price of the put is closest to:
- $28.25.
- $30.00.
- $108.25.
Xem thêm: Bài tập môn Derivatives CFA Level 1 có đáp án (PDF Free Download)
2. Bài tập Derivatives CFA Level 2
Question 1: At the inception of a market-rate plain vanilla swap, the value of the swap to the fixed-rate payer is:
- positive.
- zero.
- either positive or negative.
Passage (Question 2-5):
Chantal DuPont is the CFO of Vetements Verdun, a manufacturer of specialty clothing and uniforms, located in northern France. The firm is currently undergoing an expansion which will require DuPont to draw down 25 million on Vetements Verdun’s credit line as a 90-day bridge loan before the mortgage closes. The money will not be needed for 60 days, at which point the interest rate will be determined. The interest rate on the loan will be based off 90-day LIBOR.
DuPont is becoming concerned because of signs that interest rates may begin to rise. The firm cannot afford to have its borrowing costs increase significantly over current rates. In response to DuPont’s concerns, the company’s CEO, Viviane Lamarre, has asked DuPont to hedge the firm’s borrowing costs, even if that entails some near-term outlays.
DuPont and Lamarre discuss entering into a forward rate agreement (FRA) to hedge Vetements Verdun’s interest rate exposure on the credit line. Current LIBOR rates are:
| LIBOR rate | |
| 30-day | 2.6% |
| 60-day | 2.8% |
| 90-day | 3.0% |
| 120-day | 3.2% |
| 150-day | 3.3% |
| 180-day | 3.4% |
They decide to go forward with the hedge and DuPont enters into the appropriate FRA for the full amount of 25 million.
In the first 30 days of the FRA, the fixed income markets rally sharply. The new set of LIBOR rates, on the thirtieth day of the FRA, is:
| LIBOR rate | |
| 30-day | 2.2% |
| 60-day | 2.4% |
| 90-day | 3.6% |
| 120-day | 3.8% |
| 150-day | 3.8% |
| 180-day | 3.8% |
At the settlement date, the interest savings on the loan term is 23,750. DuPont tells Lamarre, “I am looking forward to cashing our settlement check for 23,750.” Lamarre adds, “Yes, and on top of that we get to borrow for 90 days at a below-market rate.” Both DuPont and Lamarre are pleased with their decision to hedge.
Question 2-5: Which statement most accurately describes a 2 x 3 forward rate agreement?
- Contract expires in two months on an underlying loan settled in three months.
- Two-month underlying interest rate on a contract settled in three months.
- Underlying loan of two month maturity under a contract that expires in three months.
Question 3-5: Which forward rate agreement would most effectively hedge Vetements Verdun’s exposure to LIBOR?
- 3 x 2.
- 2 x 5.
- 2 x 3
Question 4-5: Which value is closest to the price of the most effective hedge for Vetements Verdun?
- 3.3%.
- 3.6%.
- 3.0%.
Question 5-5: What must the 90-day LIBOR rate have been at the expiration of the contract?
- 3.6%.
- 4.0%.
- 3.4%.
Xem thêm: Bài tập môn Derivatives CFA Level 2 có đáp án (PDF Free Download)
3. Bài tập Derivatives CFA Level 3
3.1. Bài tập trắc nghiệm
Question 1: An investor is interested in buying KPQ shares, but finds the current trading price of $128 too high. The investor is willing to pay $115 per share. Which of the following strategies is most appropriate for the investor?
- Buy $115 strike price calls.
- Enter into a $115 strike price collar.
- Sell $115 strike price puts.
Question 2: Buying a call option on a short position in an underlying security has the same payoff structure at option expiration as a:
- short call.
- long put.
- long put combined with a short call.
Question 3: A portfolio manager with a short position in an underlying security who expects no price movement in the security over the next 6 months is least likely to benefit from:
- selling a 6-month put and buying a 6-month call on the security.
- selling a 6-month call on the security.
- selling a 6-month put on the security.
Question 4: An option trader expects that a telecommunications company will make a significant announcement tomorrow about its recent acquisition, either announcing large profits from the acquisition, or large losses. The company’s shares are currently trading at $105. The news could cause a 20% change in the share price over the next week, after which the share price is expected to stabilize. Options with 1-week maturities are available. Which of the following strategies is most appropriate for the trader?
- Bull call spread by buying a $105 strike call and selling a $126 strike call.
- Short at-the-money straddle.
- Long at-the-money straddle.
Question 5: Assume that the current price of a stock is $100. A call option on that stock with an exercise price of $97 costs $7. A call option on the stock with the same expiration and an exercise price of $103 costs $3. Using these options what is the expiration profit of a bear call spread if the stock price is equal to $110?
- -$2.
- $2.
- -$6.
3.2. Bài tập tự luận
Viteos Capital Management Case Scenario
Viteos Capital Management (VCM) specializes in different asset structures and options strategies. It is well known for its in-depth analysis and for seeking exceptional outcomes for retail and institutional clients. Ivan Li, risk manager at VCM, meets with three of the firm’s clients. The first meeting is with the Oriel Foundation, a new client of VCM. The foundation wants to discuss its equity position in Harris Industrials (HRI). Neel Aman is the head of the foundation’s investment committee. He informs Li that the foundation’s portfolio holds 100,000 shares of HRI. His research team believes that the stock is currently trading close to its peak of 56 per share and will likely stabilize around that level. Aman adds that the investment policy statement allows using derivatives, and he asks Li to recommend an option strategy that will earn a return on the position. Li gathers the information given in Exhibit 1 to explore various strategies for his client.
Sunny Kumar, another client of the firm, does not currently own HRI shares but asks Li to explain the profit potential of a bear put spread strategy. In addition, Kumar wants to know the profit potential of a collar strategy if he purchases the stock. He also inquires about the delta of a put and call option. In response, Li prepares notes to share with Kumar that discuss a delta for a 100 shares stock position and shows his analysis of two option strategies:
I: A bear put spread using the 3-month $53 and $58 strike options.
II: A collar assuming Kumar purchases HRI at $55.50 and using the 3-month strike options.
Exhibit 1: Harris Industrials Current Stock Price: 55.75; 1-month MAR 56 Call at $0.95, Harris Industrials 3-month European Options
| Exercise Price | Call Price | Call Delta | Put Price | Put Delta |
| $45 | $10.75 | 0.97 | $0.20 | -0.028 |
| $53 | $3.05 | 0.88 | $1.12 | -0.120 |
| $55.50 | $1.66 | 0.61 | $1.90 | -0.400 |
| $58 | $1.06 | 0.46 | $3.11 | -0.520 |
| $65 | $0.03 | 0.18 | $10.90 | -0.720 |
A. Discuss the option strategy Li is most likely to recommend to the foundation. State two limitations of this strategy for the foundation.
B. Based on Exhibit 1, calculate the following:
i. profit or loss per share from investing in strategy I assume HRI’s share price at expiration is $54.
ii. profit or loss per share from investing in strategy II assume HRI’s share price at expiration is $56.
C. Determine the following:
i. position delta of a protective put and covered call if Kumar is long 100 shares of HRI and buys one contract of ATM put or one contract of ATM call.
ii. put gain or loss based on Exhibit 1, if HRI stock price increases from 55.75 to 55.85 and put delta of -0.400.
Show your calculations.
A third client, Karen Wu, tells Li that she has found out that OptumRay Pharmaceuticals (OPR) will introduce a new drug to treat Alzheimer’s disease in three months. Wu believes this new drug introduction will have a positive effect on the share price. Currently, the stock is trading at 50. Until the excitement associated with this announcement starts to affect the stock price, Wu is confident that the stock will stay around the current level. Wu asks Li to recommend a strategy to benefit from this bullish outlook. Li collects the following information related to OPR’s option prices presented in Exhibit 2.
Exhibit 2 Option Prices for OptumRay Pharmaceuticals. Underlying stock price = 50
| Exercise Price | One-month Option | Three-month Option* |
| 45 | 4.95 | 6.35 |
| 50 | 1.44 | 3.60 |
| 55 | 0.20 | 1.80 |
| Theta (daily) | ||
| 45 | -0.009 | -0.013 |
| 50 | -0.037 | -0.016 |
| 55 | -0.018 | -0.015 |
*120 days till the expiration of the 3-month options.
D. Based on Exhibit 2, determine the option strategy most likely recommended by Li for the OPR stock. Justify your response. Calculate the cost and the initial theta (daily price erosion) of the position. Show your calculations.
Xem thêm: Bài tập môn Derivatives CFA Level 3 có đáp án (PDF Free Download)
Ngoài ra bạn có thể theo một khóa học về chứng chỉ CFA, nơi có thể giúp bạn định hướng và cung cấp đầy đủ tài liệu ôn thi. Nếu bạn đang cần tư vấn về lộ trình học và ôn tập CFA, đừng ngần ngại liên lạc với Taca Academy!
- Khóa học CMA luyện thi Chứng chỉ Kế toán quản trị Hoa Kỳ (U.S CMA)
- DipIFR – chứng chỉ lập báo cáo tài chính quốc tế (Level 2)
- Chuyển đổi báo cáo tài chính từ VAS – IFRS
- Khoá học IFRS toàn diện (CertIRF, DipIFR, VAS to IFRS)
Taca International Certificate,



ĐĂNG KÝ TƯ VẤN KHÓA HỌC
Vui lòng để lại thông tin liên lạc để chúng tôi có thể tư vấn rõ hơn về các khóa học
Trụ sở chính
Tầng 2 Toà A Chelsea Residences, Số 48 Trần Kim Xuyến, Q. Cầu Giấy, TP. Hà Nội
Hotline: 0985 611 911
Chi nhánh
Vincom Đồng Khởi, Quận 1, TP. HCM
Hotline: 0947 511 911